The Card Surcharge Ban Is Here. Here’s What It Actually Means for Your Business.
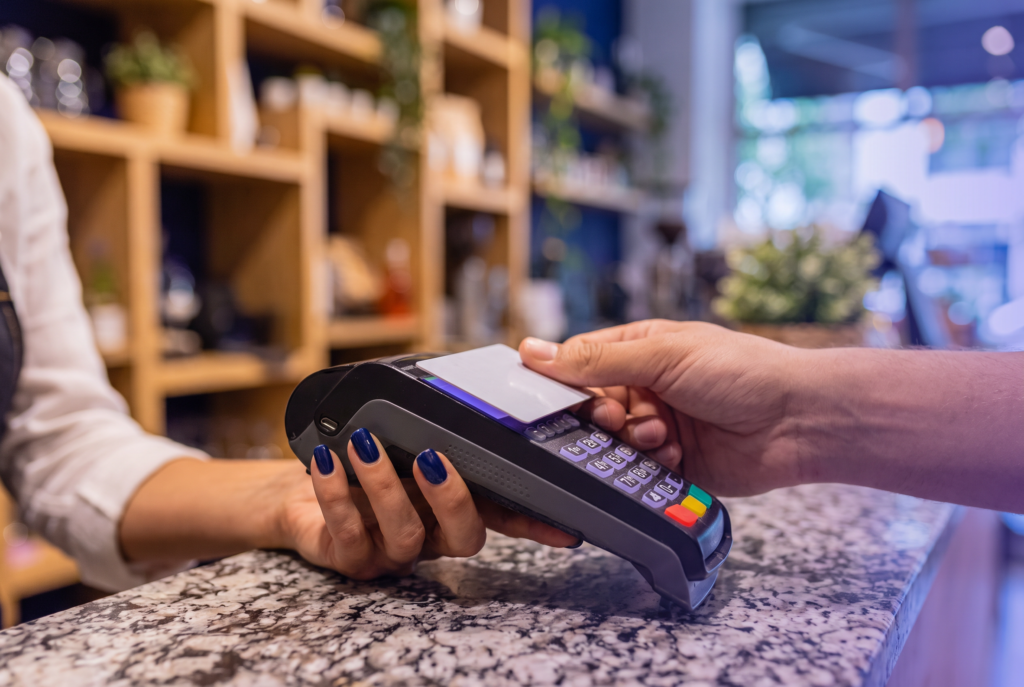
If you’ve tapped a card anywhere in Australia over the past week, you might have noticed something missing: that little extra line on the screen. The one that added 38 cents to your coffee or a couple of dollars to your dinner bill.
That’s because, as of 1 October 2026, card surcharges are gone.
For customers, it’s a simple win. For small business owners, it’s a bit more complicated. So let’s cut through it — what changed, what’s still allowed, and what you should be doing about it right now.
What actually changed?
Back in March, the Reserve Bank of Australia finished a long review of what businesses pay to accept cards. Its conclusion was blunt: surcharging wasn’t working the way it was meant to anymore.
The result is a ban on surcharges for debit, prepaid and credit card payments made on the eftpos, Visa and Mastercard networks. That includes payments through mobile wallets like Apple Pay and Google Pay that run on those cards. American Express has also said it will remove surcharging on its cards.
This isn’t a “soft guideline”. It’s being enforced through the card networks themselves, which means many payment providers and accounting platforms have simply switched the surcharge option off. If your terminal or invoicing software used to add the fee automatically, there’s a good chance it’s already stopped.
Why did the RBA do this?
A few reasons came out of the review:
- Surcharges had become hard to avoid. Cash now makes up a small slice of in-person payments, so “just pay cash” isn’t a realistic alternative for most customers.
- Many businesses were charging one flat rate across every card, which defeated the original purpose, nudging people towards cheaper payment methods.
- The old rules were hard to enforce. Excessive surcharges were a constant source of complaints.
The RBA’s view is that the price on the shelf should be the price you pay. No surprises at the checkout.
The bit that helps you: lower card fees
The ban didn’t arrive on its own. Alongside it, the RBA lowered the caps on interchange fees — the portion of your merchant fee that goes to the card-issuing bank — for domestic debit and consumer credit cards. That also started on 1 October.
Two more changes are coming on 1 April 2027:
- A 1% cap on interchange for foreign-issued cards, which matters if you serve tourists or sell overseas.
- Clearer merchant statements, so you can actually see what you’re paying and compare providers properly.
The idea is that your underlying cost of accepting cards should come down. Whether that saving actually reaches you depends a lot on your payment provider — which is why the next section matters.
“So I just eat the cost?”
Not necessarily. You have a few options, and most businesses will use a mix:
1. Build it into your prices. This is what the RBA expects most surcharging businesses to do — fold card costs into your prices, the same way you already handle rent, wages and stock. Because underlying card costs should be lower, you’ll likely need to lift prices by less than your old surcharge was.
2. Absorb it. For some businesses the fee is small enough that it’s simply a cost of doing business — especially when card payments mean faster payment and less time chasing invoices.
3. Shop around. This is the big one. Many small businesses have been on the same merchant plan for years without checking it. With the market shaking up, now’s the time to compare.
One thing not to do: rename the surcharge. A “card handling fee” or “service fee” that happens to land exactly where your old surcharge was is precisely the kind of workaround these rules are designed to catch. If the fee only appears when someone pays by card, it’s a surcharge — whatever you call it.
We had to rethink things too
This isn’t theory for us. When we looked at how payments worked in the SBC marketplace, card processing fees were landing on us, and with surcharging off the table that simply wasn’t sustainable. So we changed course: rather than running a shop, we’ve put our energy into what members actually use — the directory, the community, events and the job board.
That’s the reality for a lot of small businesses right now. The rules changed, so the setup has to change too. It’s not a crisis, but it does deserve an hour of your attention.
Your quick checklist
If you haven’t done these yet, block out some time this week:
- Check every place a surcharge might live — your EFTPOS terminal, online checkout, payment links, invoice templates, booking systems and any website plugins.
- Remove surcharge mentions from signage, menus, receipts, your website and quote templates.
- Pull your last three months of merchant statements and work out what card payments are really costing you as a percentage.
- Ask your provider what they’re charging you now, after the 1 October interchange changes. If the answer is vague, that tells you something.
- Get two or three comparison quotes from other payment providers.
- Review your pricing with real numbers, not guesses. Small, considered adjustments beat a panicked across-the-board increase.
- Tell your regulars if prices are moving. Most customers appreciate honesty far more than they resent a small change.
The bottom line
The surcharge ban is one of the biggest shake-ups to how Australians pay in two decades. For customers, it’s simpler. For small business owners, it’s one more thing to manage — but it’s also a genuine nudge to look at costs you may have been ignoring for years.
Do the checklist, have a conversation with your provider, and talk to your accountant or bookkeeper if you’re unsure how it affects your margins.
And if you want to hear how other small business owners are handling it — what they’ve done with pricing, which providers they’ve switched to — that’s exactly the kind of conversation happening in the SBC community right now.
This article is general information only and isn’t financial or legal advice. For advice on your situation, speak to your accountant, business adviser or payment provider. For official guidance, see business.gov.au and the Reserve Bank of Australia.
Responses